مشتری بزرگ، حساب خوب نیست: وقتی سفارش سود را میبلعد
فروش بالا همیشه به معنای سود خوب نیست. گاهی هزینه خدمت، استثناها و ریسک وصول، حاشیه واقعی یک حساب بزرگ را میبلعند.
فهرست مطالب
در بازار صنعتی، عدد فروش قدرت عجیبی برای فریب دادن دارد. یک مشتری بزرگ است، سفارشهایش روی گزارش خوب دیده میشود، تیم فروش نامش را با افتخار میآورد و مدیر هم طبیعی است که نگران از دستدادنش باشد. اما سؤال مهمتری وجود دارد که معمولاً دیر پرسیده میشود: این حساب، بعد از همه دردسرهایی که برایش میکشیم، واقعاً برای ما سود میسازد؟
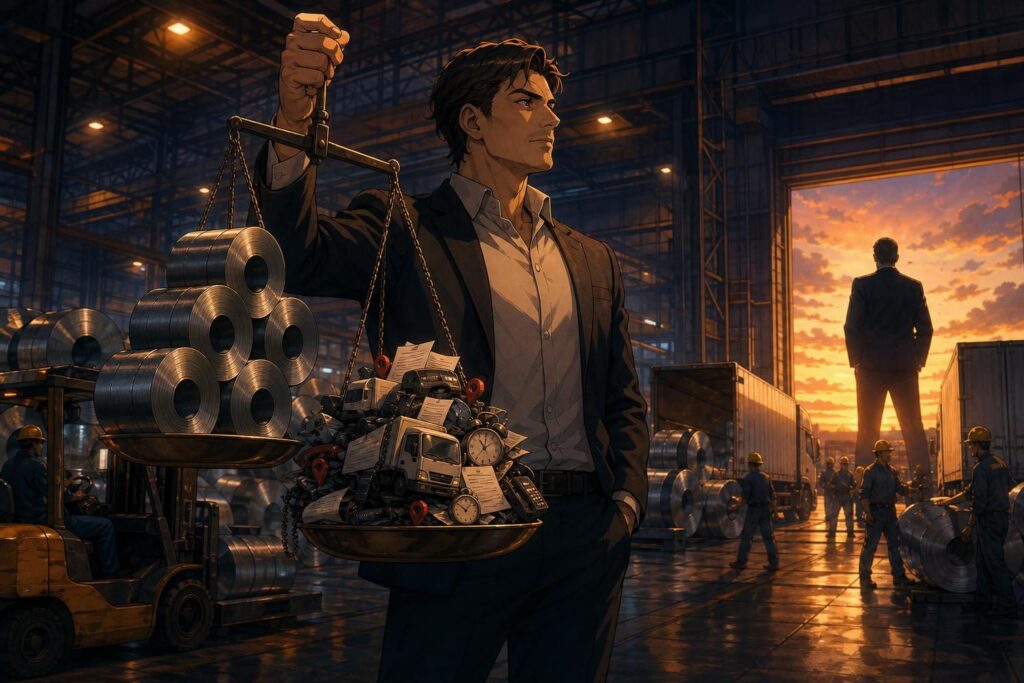
در فروش و کسبوکار صنعتی، این تفاوت زیاد دیده میشود که مشتری بزرگ و مشتری خوب یک چیز نیستند. مشتری بزرگ ممکن است حجم خرید بالایی داشته باشد، اما همزمان عملیات را فرسوده کند، تیم فروش را درگیر استثناهای بیپایان نگه دارد، انبار را بههم بریزد، حمل را گران کند و پولش را آنقدر دیر بدهد که سود روی کاغذ، در عمل تبدیل به هزینه تأمین مالی شود.
در فروش فولاد، خیلی راحت میشود با دیدن اختلاف قیمت خرید و فروش احساس رضایت کرد. کالا را با یک قیمت خریدهایم، با قیمت بالاتر فروختهایم و ظاهراً حاشیه مشخص است. ولی این فقط ابتدای محاسبه است، نه انتهای آن. برای رساندن همان کالا به دست مشتری چه کارهایی کردهایم؟ چند بار سفارش تغییر کرده؟ چند تماس فوری گرفتهایم؟ حمل چگونه انجام شده؟ اسناد چند بار اصلاح شدهاند؟ پول چه زمانی و با چه ریسکی برمیگردد؟
مسئله این نیست که هر خدمتی به مشتری هزینه دارد؛ این بدیهی است. مسئله از جایی شروع میشود که این هزینهها دیده نمیشوند یا به اسم «حفظ رابطه» بدون تصمیم روشن پذیرفته میشوند. در آن وضعیت، فروشنده تصور میکند دارد مشتری را نگه میدارد، عملیات تصور میکند دارد آتش خاموش میکند و مالی میبیند که سود ادعاشده هنوز وارد حساب نشده است. هر واحد بخشی از واقعیت را میبیند، اما کسی اقتصاد کل حساب را نمیبیند.
اولین علامت هشدار، سفارشهای خرد و پرتکرار است. ممکن است مجموع خرید مشتری در پایان ماه بزرگ باشد، اما اگر آن حجم از دهها سفارش کوچک ساخته شده باشد، هزینه پردازش آن با یک یا دو سفارش برنامهریزیشده قابلمقایسه نیست. هر سفارش، بررسی موجودی، هماهنگی، صدور سند، بارگیری، پیگیری و احتمال خطا دارد. وقتی تعداد درخواستها زیاد میشود، هزینه فقط در واحد مالی یا انبار نمیماند؛ تمرکز تیم را هم میخورد.
دومین علامت، فوریت دائمی است. مشتریای که گاهی در شرایط واقعی به تحویل فوری نیاز دارد، لزوماً مشتری بدی نیست. اما وقتی «فوری» تبدیل به الگوی عادی سفارشدادن میشود، در واقع او بخشی از بینظمی یا کمبود برنامهریزی خودش را به کسبوکار شما منتقل کرده است. هزینه این انتقال ممکن است در کرایه حمل، اضافهکاری، جابهجایی اولویت مشتریان دیگر یا حتی تصمیمهای عجولانه خرید ظاهر شود. اگر این هزینه در شرایط معامله دیده نشده باشد، شما دارید آن را از حاشیه خودتان پرداخت میکنید.
سومین علامت، تغییر مداوم سفارش است. تغییر در مقدار، سایز، محل تخلیه، زمان ارسال یا مشخصات اسناد، همیشه بیدلیل رخ نمیدهد و نباید با مشتری مثل متهم برخورد کرد. اما تکرار این تغییرها یک واقعیت عملیاتی میسازد. کالایی که برای آن رزرو شده، برنامه باری که تغییر کرده، سندی که باید اصلاح شود و نیرویی که دوباره هماهنگ میکند، همه هزینه دارند. خطر اصلی اینجاست که چون هر تغییر بهتنهایی کوچک به نظر میرسد، مجموع آنها هیچوقت به حساب مشتری برنمیگردد.
چهارمین علامت، خدمت خاص بدون مرز روشن است. تحویل در ساعت غیرمعمول، حمل با شرایط ویژه، بستهبندی متفاوت، کنترلهای اضافه، کسری یا پیچیدگی اسناد، نگهداشتن موجودی برای مدت طولانی یا پاسخگویی خارج از روال، میتوانند برای یک حساب ارزشمند کاملاً منطقی باشند. مشکل خودِ خدمت ویژه نیست. مشکل این است که خدمت ویژه را مثل یک لطف مبهم ارائه کنیم، نه مثل بخشی از توافق تجاری با دامنه، هزینه و مسئول مشخص.
پنجمین علامت، فاصله بین فروش و وصول است. بعضی حسابها از نظر فروشنده عالیاند، چون سفارش میدهند و حجم میبرند. اما اگر شرایط پرداختشان مدام کش پیدا کند، اگر برای هر وصول نیاز به پیگیری غیرعادی باشد، یا اگر اختلاف و کسری اسناد پرداخت را عقب بیندازد، باید پذیرفت که این هم بخشی از اقتصاد مشتری است. سودی که دیر و با ریسک برمیگردد، با سودی که طبق توافق و قابلپیشبینی وصول میشود یکی نیست.
من پیشنهاد نمیکنم فروشنده با دیدن یکی از این علامتها سریع مشتری را رد کند یا در مذاکره حالت تنبیهی بگیرد. بازار واقعی اینقدر ساده نیست. بعضی مشتریها از نظر راهبردی مهماند؛ شاید به دلیل اعتبار بازار، ثبات حجم، امکان توسعه همکاری یا نقشی که در برنامه کلی کسبوکار دارند. اما ارزش راهبردی هم نباید بهانهای برای ندیدن هزینه باشد. اگر قرار است هزینهای آگاهانه پذیرفته شود، باید واقعاً آگاهانه باشد، نه محصول عادت، ترس یا گزارش فروش.
پیش از پذیرفتن یک سفارش خاص یا دادن یک امتیاز تازه، فروش باید چند سؤال ساده اما جدی بپرسد. این درخواست، یک استثناست یا دارد تبدیل به عادت میشود؟ چه کسی در عملیات و مالی، هزینه یا ریسک آن را تأیید میکند؟ اگر همین سطح خدمت به همه سفارشهای این مشتری تعمیم پیدا کند، هنوز حساب قابلدفاع است؟ در برابر این امتیاز چه چیزی میگیریم: حجم قابلپیشبینی، پرداخت بهتر، تعهد زمانی، کاهش تغییرات یا فقط یک وعده مبهم؟ و مهمتر از همه، اگر این درخواست را نپذیریم، واقعاً چه چیزی را از دست میدهیم؟
این سؤال آخر مهم است، چون در بسیاری از مذاکرهها ما پیش از آنکه مشتری تهدیدی مطرح کند، خودمان از دستدادن او را قطعی فرض میکنیم. بعد، امتیاز میدهیم تا مسئلهای را حل کنیم که شاید اصلاً وجود خارجی نداشته باشد. فروش حرفهای فقط توانایی گفتن «بله» نیست؛ توانایی دیدن هزینه بلهگفتن و طراحی یک بله مشروط است. گاهی جواب درست این است که سفارش را میپذیریم، اما با زمان تحویل متفاوت. گاهی میپذیریم، اما با حداقل مقدار سفارش یا هزینه حمل مشخص. گاهی هم میپذیریم، اما شرایط پرداخت باید اصلاح شود.
برای اینکه این بحث از سلیقه افراد خارج شود، یک جلسه کوتاه و منظم بین فروش، مالی و عملیات لازم است. نه جلسهای برای سرزنش فروش که چرا تعهد داده، و نه جلسهای برای متهمکردن عملیات به سختگیری. موضوع جلسه باید یک حساب یا یک الگوی سفارش مشخص باشد. فروش توضیح دهد چرا این مشتری و این درخواست مهم است. عملیات بگوید اجرای آن چه فشاری ایجاد میکند. مالی، وضعیت وصول و ریسک را روشن کند. سپس تصمیم ثبت شود: شرایط معامله اصلاح میشود، سطح خدمت تغییر میکند، یا هزینه به دلیل ارزش راهبردی پذیرفته میشود.
نکته مهم، ثبت تصمیم است. اگر توافق میکنیم برای یک مشتری موجودی نگه داریم، حمل خاص انجام دهیم یا انعطاف بیشتری در پرداخت نشان دهیم، باید معلوم باشد این تصمیم تا چه زمانی معتبر است، مسئول بازبینی آن کیست و چه چیزی نشان میدهد که هنوز ارزش ادامهدادن دارد. بدون این شفافیت، استثناها خیلی زود به حق دائمی مشتری تبدیل میشوند و تیم شما هر بار مجبور است از صفر درباره چیزی مذاکره کند که قبلاً بیصدا واگذار شده است.
حساب خوب، حسابی نیست که فقط عدد فروش را بالا ببرد. حساب خوب، حسابی است که اقتصادش قابلفهم و قابلدفاع باشد؛ بدانیم برای آن چه خدمتی میدهیم، چه ریسکی میپذیریم، چه چیزی در مقابل میگیریم و کجا باید مرز بگذاریم. ممکن است یک مشتری بزرگ، با اصلاح چند شرط، به حسابی بسیار خوب تبدیل شود. ممکن است هم بعد از دیدن واقعیت، بفهمیم بخشی از فروش ما فقط شلوغی تولید میکرده است، نه سود.
در نهایت، مسئله مخالفت با رشد یا بیاحترامی به مشتری بزرگ نیست. مسئله این است که فروش را از حجم جدا نکنیم. هر سفارشی که وارد میشود، فقط کالا از انبار خارج نمیکند؛ زمان، تمرکز، ظرفیت حمل، اعتبار و تحمل ریسک سازمان را هم مصرف میکند. وقتی این مصرف را ببینیم، سه انتخاب روشن داریم: شرایط معامله را اصلاح کنیم، سطح خدمت را تغییر دهیم، یا هزینه را بهدلیل یک ارزش راهبردی آگاهانه بپذیریم. تصمیم بد، انتخاب هیچکدام نیست؛ یعنی ادامهدادن همان مسیر، فقط چون عدد فروش هنوز خوب به نظر میرسد.
فروش خوب فقط بستن سفارش نیست. فروش خوب یعنی سفارشی ببندیم که شرکت بتواند آن را با سود، نظم و احترام به تعهدات دیگرش اجرا کند. این تفاوت شاید در گزارش ماهانه کوچک دیده شود، اما در کیفیت کسبوکار، تفاوتی تعیینکننده است.
وقتی اقتصاد واقعی هر حساب روشن شود، مذاکره هم بالغتر میشود. دیگر بحث فقط این نیست که مشتری چه تخفیفی میخواهد یا فروشنده چقدر میتواند کوتاه بیاید. بحث این میشود که چه مدل همکاریای برای هر دو طرف قابلاجرا و پایدار است. این گفتوگو شاید در ابتدا سختتر باشد، اما از آن رابطهای حرفهایتر ساخته میشود؛ رابطهای که نه با لطفهای پنهان، بلکه با تعهدهای روشن دوام میآورد.
اگر امروز بخواهم فقط یک کار عملی پیشنهاد بدهم، این است: پنج حساب پرفروش را انتخاب کنید و برای هرکدام، جدا از مبلغ فروش، تعداد سفارشها، تعداد فوریتها، تغییرات، خدمات ویژه، وضعیت وصول و درگیری عملیاتی را مرور کنید. لازم نیست از روز اول مدل پیچیدهای بسازید. هدف اولیه، دیدن چیزی است که تا امروز در عدد فروش پنهان بوده. خیلی از تصمیمهای بهتر، نه با داشبوردهای بزرگ، بلکه با همین دیدن ساده شروع میشوند.
ممکن است نتیجه این مرور خوشایند نباشد. شاید بفهمید مشتریای که همیشه از او بهعنوان موفقیت یاد میکردید، فشار اصلی را به تیم وارد میکند. اما این کشف برای حذف مشتری نیست؛ برای مدیریتکردن رابطه است. تا وقتی هزینه خدمت نامرئی است، نه فروش میتواند درست مذاکره کند، نه عملیات میتواند درست برنامهریزی کند و نه مدیریت میتواند درباره سود واقعی تصمیم بگیرد.
در بازارهایی که حاشیه زیر فشار است، اشتباه رایج این است که همه نگاهها فقط به قیمت خرید و قیمت فروش برود. قیمت مهم است، اما همه داستان نیست. سود در فاصله میان سفارش تا وصول هم ساخته میشود یا از بین میرود. هر کس این فاصله را بهتر ببیند، لازم نیست برای رشد فقط بیشتر بفروشد؛ میتواند بهتر بفروشد.
مشتری بزرگ را با احترام نگه دارید، اما با چشم باز. حجم خرید او را ببینید، ولی هزینه خدمت و ریسکی را که به همراه میآورد هم ببینید. یک حساب خوب، رابطهای است که هر دو طرف بتوانند روی آن حساب کنند؛ نه رابطهای که یک طرف مدام درخواست جدید میسازد و طرف دیگر، بیآنکه بداند چه چیزی را خرج میکند، فقط تلاش میکند نه نشنود.
این مرور، کاری یکباره نیست. شرایط بازار، رفتار مشتری و فشار عملیاتی در طول زمان تغییر میکند؛ حسابی که امسال قابلدفاع است، ممکن است سال بعد دیگر نباشد، یا برعکس. بهتر است بازبینی حسابهای مهم به یک عادت دورهای تبدیل شود، نه واکنشی که فقط وقتی سود کم میشود سراغش میرویم.
سود واقعی، معمولاً در فاکتور پنهان نمیشود؛ در رفتوآمدهای اطراف فاکتور پنهان میشود. در تماسهای فوری، اصلاحهای پیدرپی، هماهنگیهای خارج از روال، بارهای کمحجم، تعهدهای شفاهی و پیگیریهای وصول. دیدن اینها بدبینی نیست. این همان احترام به کسبوکاری است که قرار است فقط شلوغ نباشد، بلکه سالم بماند.
In industrial markets, sales figures have a strange power to mislead. A customer is large, their orders look impressive on the report, the sales team mentions their name with pride, and naturally management worries about losing them. But there is a more important question that is usually asked too late: after all the effort we put into this account, does it actually make money for us?
In industrial sales and business, this distinction shows up often: a large customer and a good customer are not the same thing. A large customer may buy in high volume while exhausting operations, keeping the sales team busy with endless exceptions, disrupting the warehouse, making transportation more expensive, and paying so late that the profit on paper becomes a financing cost in reality.
In steel sales, it is easy to feel satisfied when we look at the gap between purchase and selling prices. We bought the material at one price, sold it at a higher price, and the margin appears clear. But that is the beginning of the calculation, not the end. What did we have to do to get that material to the customer? How many times did the order change? How many urgent calls did we handle? How was transportation arranged? How many times were documents corrected? When does the money come back, and with what risk?
The issue is not that every service provided to a customer has a cost; that is obvious. The issue begins when those costs are invisible, or accepted in the name of “maintaining the relationship” without a clear decision. In that situation, sales thinks it is retaining the customer, operations thinks it is putting out fires, and finance sees that the claimed profit has still not reached the bank. Each function sees part of the truth, but no one sees the full economics of the account.
The first warning sign is frequent, small orders. A customer’s total purchases may be substantial at the end of the month, but if that volume is made up of dozens of small orders, the cost of handling it is not comparable to one or two planned orders. Every order involves inventory checks, coordination, documentation, loading, follow-up, and the possibility of error. As requests multiply, the cost does not stay only with finance or the warehouse; it also disrupts the team’s focus.
The second sign is permanent urgency. A customer who occasionally needs urgent delivery in a genuine situation is not necessarily a bad customer. But when “urgent” becomes their standard way of ordering, they are effectively transferring part of their own disorder or lack of planning to your business. The cost of that transfer may appear in freight charges, overtime, shifting other customers’ priorities, or even rushed purchasing decisions. If that cost is not reflected in the terms of the deal, you are paying for it out of your own margin.
The third sign is constant order change. Changes in quantity, size, unloading location, delivery time, or document specifications do not always happen without reason, and customers should not be treated as defendants. But repeated changes create an operational reality. Material has been reserved, a shipping plan has changed, a document must be corrected, and someone must coordinate again. The main danger is that, because each change seems small on its own, their total cost is never charged back to the account.
The fourth sign is special service with no clear boundary. Delivery at unusual hours, transportation under special conditions, different packaging, extra checks, document shortages or complexity, holding inventory for a long period, or responding outside normal routines can all be completely reasonable for a valuable account. The problem is not special service itself. The problem is providing it as a vague favor rather than as part of a commercial agreement with a defined scope, cost, and owner.
The fifth sign is the gap between sales and collection. Some accounts look excellent to a salesperson because they place orders and take volume. But if their payment terms keep extending, if every collection requires unusual follow-up, or if document disputes and shortages delay payment, that too must be accepted as part of the customer’s economics. Profit that returns late and at risk is not the same as profit collected predictably according to the agreement.
I am not suggesting that a salesperson should quickly reject a customer at the first sign of one of these issues, or take a punitive tone in negotiation. The real market is not that simple. Some customers are strategically important, perhaps because of market credibility, stable volume, room for expansion, or the role they play in the broader business plan. But strategic value should not become an excuse for ignoring cost. If a cost is to be accepted knowingly, it must truly be accepted knowingly, not as the result of habit, fear, or a sales report.
Before accepting a particular order or granting a new concession, sales should ask a few simple but serious questions. Is this request an exception, or is it becoming a habit? Who in operations and finance confirms its cost or risk? If this level of service extends to every order from this customer, is the account still defensible? What do we receive in return for this concession: predictable volume, better payment, a time commitment, fewer changes, or merely a vague promise? And most importantly, if we do not accept this request, what are we actually going to lose?
That last question matters because in many negotiations, before the customer even makes a threat, we assume losing them is certain. Then we grant concessions to solve a problem that may not even exist. Professional selling is not only the ability to say yes; it is the ability to see the cost of saying yes and to design a conditional yes. Sometimes the right answer is that we accept the order, but with a different delivery date. Sometimes we accept it, but with a minimum order quantity or a defined freight charge. Sometimes we accept it, but the payment terms must change.
To move this discussion beyond individual preferences, a short and regular meeting between sales, finance, and operations is needed. Not a meeting to blame sales for making commitments, and not a meeting to accuse operations of being rigid. The topic should be one specific account or a specific ordering pattern. Sales explains why the customer and request matter. Operations explains what pressure execution creates. Finance clarifies collection status and risk. Then the decision is recorded: the deal terms are revised, the service level changes, or the cost is accepted because of strategic value.
Recording the decision matters. If we agree to hold inventory for a customer, arrange special transport, or show more flexibility on payment, it should be clear how long that decision is valid, who will review it, and what will show that it is still worth continuing. Without that clarity, exceptions quickly become the customer’s permanent entitlement, and your team must renegotiate from zero every time something that was quietly given away comes up again.
A good account is not simply one that raises the sales number. A good account is one whose economics are understandable and defensible: we know what service we provide, what risk we accept, what we receive in return, and where we need to draw a line. A large customer may become an excellent account after a few terms are corrected. Or, after seeing reality, we may realize that part of our sales was only creating activity, not profit.
Ultimately, this is not about opposing growth or disrespecting a large customer. It is about not separating sales from volume. Every order that comes in does not merely move material out of the warehouse; it also consumes the organization’s time, focus, transport capacity, credit, and tolerance for risk. Once we see that consumption, we have three clear choices: revise the deal terms, change the service level, or knowingly accept the cost because of strategic value. The bad decision is choosing none of them: continuing on the same path only because the sales figure still looks good.
Good selling is not merely closing an order. Good selling means closing an order that the company can execute profitably, in an orderly way, and without disrespecting its other commitments. This difference may look small in a monthly report, but it is decisive in the quality of the business.
When the real economics of each account become visible, negotiation becomes more mature as well. The discussion is no longer only about the discount the customer wants or how much the salesperson can give up. It becomes about what model of cooperation is workable and sustainable for both sides. That conversation may be harder at first, but it builds a more professional relationship: one that lasts through clear commitments, not hidden favors.
If I were to suggest just one practical action today, it would be this: choose five high-revenue accounts and review, for each one, not only sales value but also the number of orders, urgent requests, changes, special services, collection status, and operational involvement. You do not need to build a complex model on day one. The first goal is to see what has been hidden inside the sales figure until now. Many better decisions begin not with large dashboards, but with this simple act of seeing.
The result of that review may not be pleasant. You may discover that a customer you have always described as a success is placing the greatest pressure on the team. But this discovery is not for eliminating the customer; it is for managing the relationship. As long as the cost to serve is invisible, sales cannot negotiate properly, operations cannot plan properly, and management cannot decide on real profit.
In markets where margins are under pressure, the common mistake is to focus all attention only on the purchase price and selling price. Price matters, but it is not the whole story. Profit is also created or destroyed in the distance between order and collection. Whoever sees that distance more clearly does not need to grow only by selling more; they can grow by selling better.
Keep the large customer with respect, but with open eyes. See their purchase volume, but also see the service cost and risk they bring with them. A good account is a relationship both sides can rely on, not one in which one side constantly creates new demands and the other, without knowing what it is spending, simply tries not to hear no.
This review is not a one-time task. Market conditions, customer behavior, and operational pressure change over time; an account that is defensible this year may not be next year, or the opposite may happen. It is better to turn the review of important accounts into a periodic habit, not a reaction we only reach for once profit has already shrunk.
Real profit is usually not hidden in the invoice itself; it is hidden in everything that happens around the invoice. In urgent calls, repeated corrections, off-process coordination, small loads, verbal commitments, and collection follow-ups. Seeing these things is not pessimism. It is respect for a business that is meant not merely to stay busy, but to stay healthy.
اگر این موضوع شبیه مسئله واقعی کسبوکار توست، از چکاپ تصمیم شروع کن.
یک مسیر کوتاه برای روشنکردن مسئله، گلوگاه تصمیم و قدم بعدی؛ بدون فرم طولانی و بدون تعهد.